Rates Fell for Four Straight Weeks
Mortgage November 16, 2026
Mortgage November 16, 2026
Rates Fell for Four Straight Weeks — Why Buyers Waited, and What Finally Moved Them
If you've been watching mortgage rates this fall, waiting for your moment, you are not alone — and the latest national numbers prove it in a way we find genuinely useful for buyers here in Henderson and Transylvania counties.
Here's the short version: rates eased, and at first, almost nobody moved. Then they eased again. And again. And on the fourth straight week of declines, buyers finally stepped off the sidelines. Understanding why it took four weeks — not one — can save you from making the most common mistake we see right now: waiting for a perfect rate that may never announce itself.
One small dip wasn't enough
Let's rewind two weeks. In the Mortgage Bankers Association's survey for the week ending October 30, the average 30-year fixed rate slipped from 7.37% to 7.30% — and total mortgage applications actually fell 1.2%. Rates dipped, but buyers didn't bite.
That sounds stubborn until you do the payment math. On a $300,000 loan, the difference between 7.37% and 7.30% is about $14 a month in principal and interest. Fourteen dollars. Nobody changes their moving plans, their school district, or their life for $14 a month — and honestly, they shouldn't. A headline that says "rates fall!" can mean almost nothing at your kitchen table, and that week, buyers knew it.
Four weeks was a different story
The declines kept coming. By the week ending November 6 — the MBA's latest survey, released November 11 — the average 30-year fixed rate had fallen for the fourth straight week, to 7.21%, the lowest since mid-September. The FHA rate slipped back below 7%, to 6.98%, which the MBA credited with helping first-time buyers in particular.
This time, buyers responded. Total applications rose 6.2%, purchase applications jumped 8%, and refinance applications rose 5%, with especially strong growth in FHA and VA purchase applications.
But read the fine print with us, because it matters: even after that jump, purchase applications were still 18% lower than the same week a year ago, and refinances were 57% lower. Buyers didn't flood back. They leaned in — cautiously, and only after a month of steady improvement added up to something they could feel. From around 7.50% to 7.21%, the saving on that same $300,000 loan is roughly $59 a month. Still not life-changing — but real, and moving in the right direction.
What this means if you're buying here
Small dips are noise; trends are signal. One week's tiny drop changes a payment by the cost of a pizza. What moved buyers nationally was a pattern — four weeks in a row. If you're waiting, wait for a pattern, not a headline.
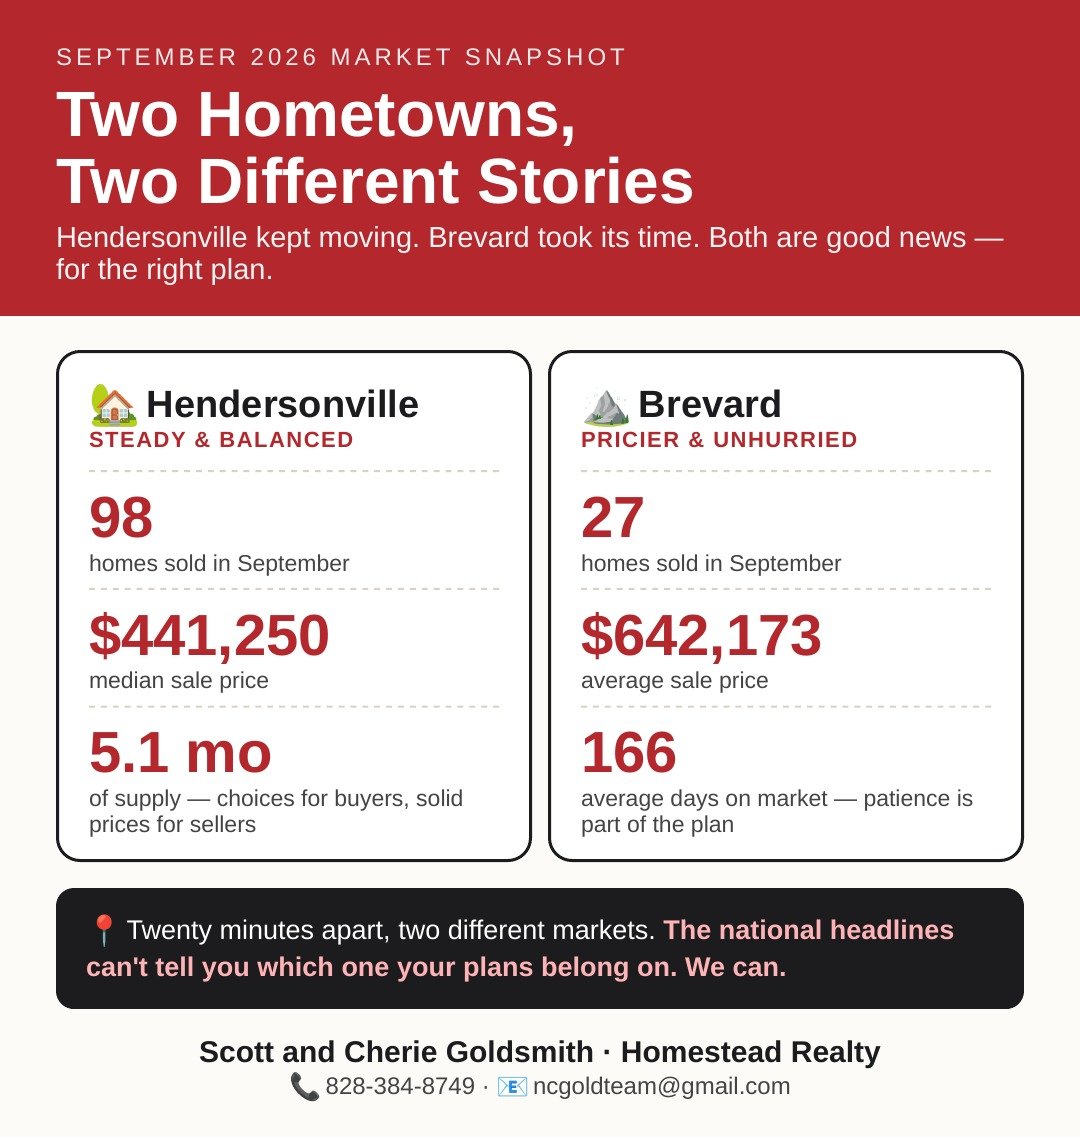
The right home doesn't wait with you. While buyers nationally were sitting out October, Hendersonville was closing 98 sales in September at a median of $441,250, in a balanced market with real choices. The home that fits your life — the level lot, the right school, the porch facing the evening sun — can sell while you're watching a rate app. Rates can be revisited later; a specific house cannot.
Buying now is not betting that rates stay high. Some of our buyers take the home they love at today's rate, with a payment they can genuinely afford, and simply keep an eye on the market afterward. If rates fall meaningfully down the road, a refinance conversation may be worth having then. That's not a promise — rates change daily, and nobody can guarantee where they'll go — it's just keeping a door open instead of standing outside the house.
And a word of caution from this very week: daily rate trackers showed rates bouncing back up within days of that November 6 low, after a hotter-than-expected inflation report. That's the whole lesson in miniature. Windows open slowly and close fast.
The bottom line
Buyers nationally needed four straight weeks of falling rates before they moved — and even then, they moved carefully. We think that's exactly the right temperament, paired with one addition: run your numbers, on the home you actually want, here in our mountains. A $14-a-month headline shouldn't move you. A home your family will love for twenty years, at a payment that fits your real budget, just might.
Curious what the math looks like on a home you've been eyeing — or whether waiting is actually the right call for you? Call us. As both your local agents and a mortgage loan originator, we can walk through both sides of that conversation honestly, in plain English.
— Scott and Cherie Goldsmith, Homestead Realty · 828-384-8749 · [email protected]
Payment examples are illustrative only — principal and interest on a 30-year fixed loan — and are not a rate quote, an offer to lend, or a guarantee of future rates. Rates change daily; talk with your lender about your own numbers.
Quick answers
What is the average 30-year fixed mortgage rate right now?
In the MBA's latest survey (week ending November 6, 2026), the average contract rate for a 30-year fixed mortgage with a conforming loan balance was 7.21% — down for the fourth straight week, and the lowest since mid-September. The average FHA rate was 6.98%.
Did lower rates bring buyers back?
Partly. Total mortgage applications rose 6.2% that week and purchase applications rose 8% — but purchases were still 18% below the same week a year ago, so buyers returned cautiously, not in a rush.
How much does a small rate drop actually save?
On a $300,000, 30-year loan, a drop from 7.37% to 7.30% saves only about $14 a month in principal and interest. Bigger, sustained moves are what change the math.
Related reading: Our September market snapshot:
Stay up to date on the latest real estate trends.
Mortgage
— Why Buyers Waited, and What Finally Moved Them
— and the One Question Every New-Construction Buyer Should Ask

Our intent is to leave a legacy that speaks of honesty, allegiance to our community and the need to do the right thing without regard for monetary gain. We are available weekdays as well as weekends, call or email us for help with all your real estate needs.